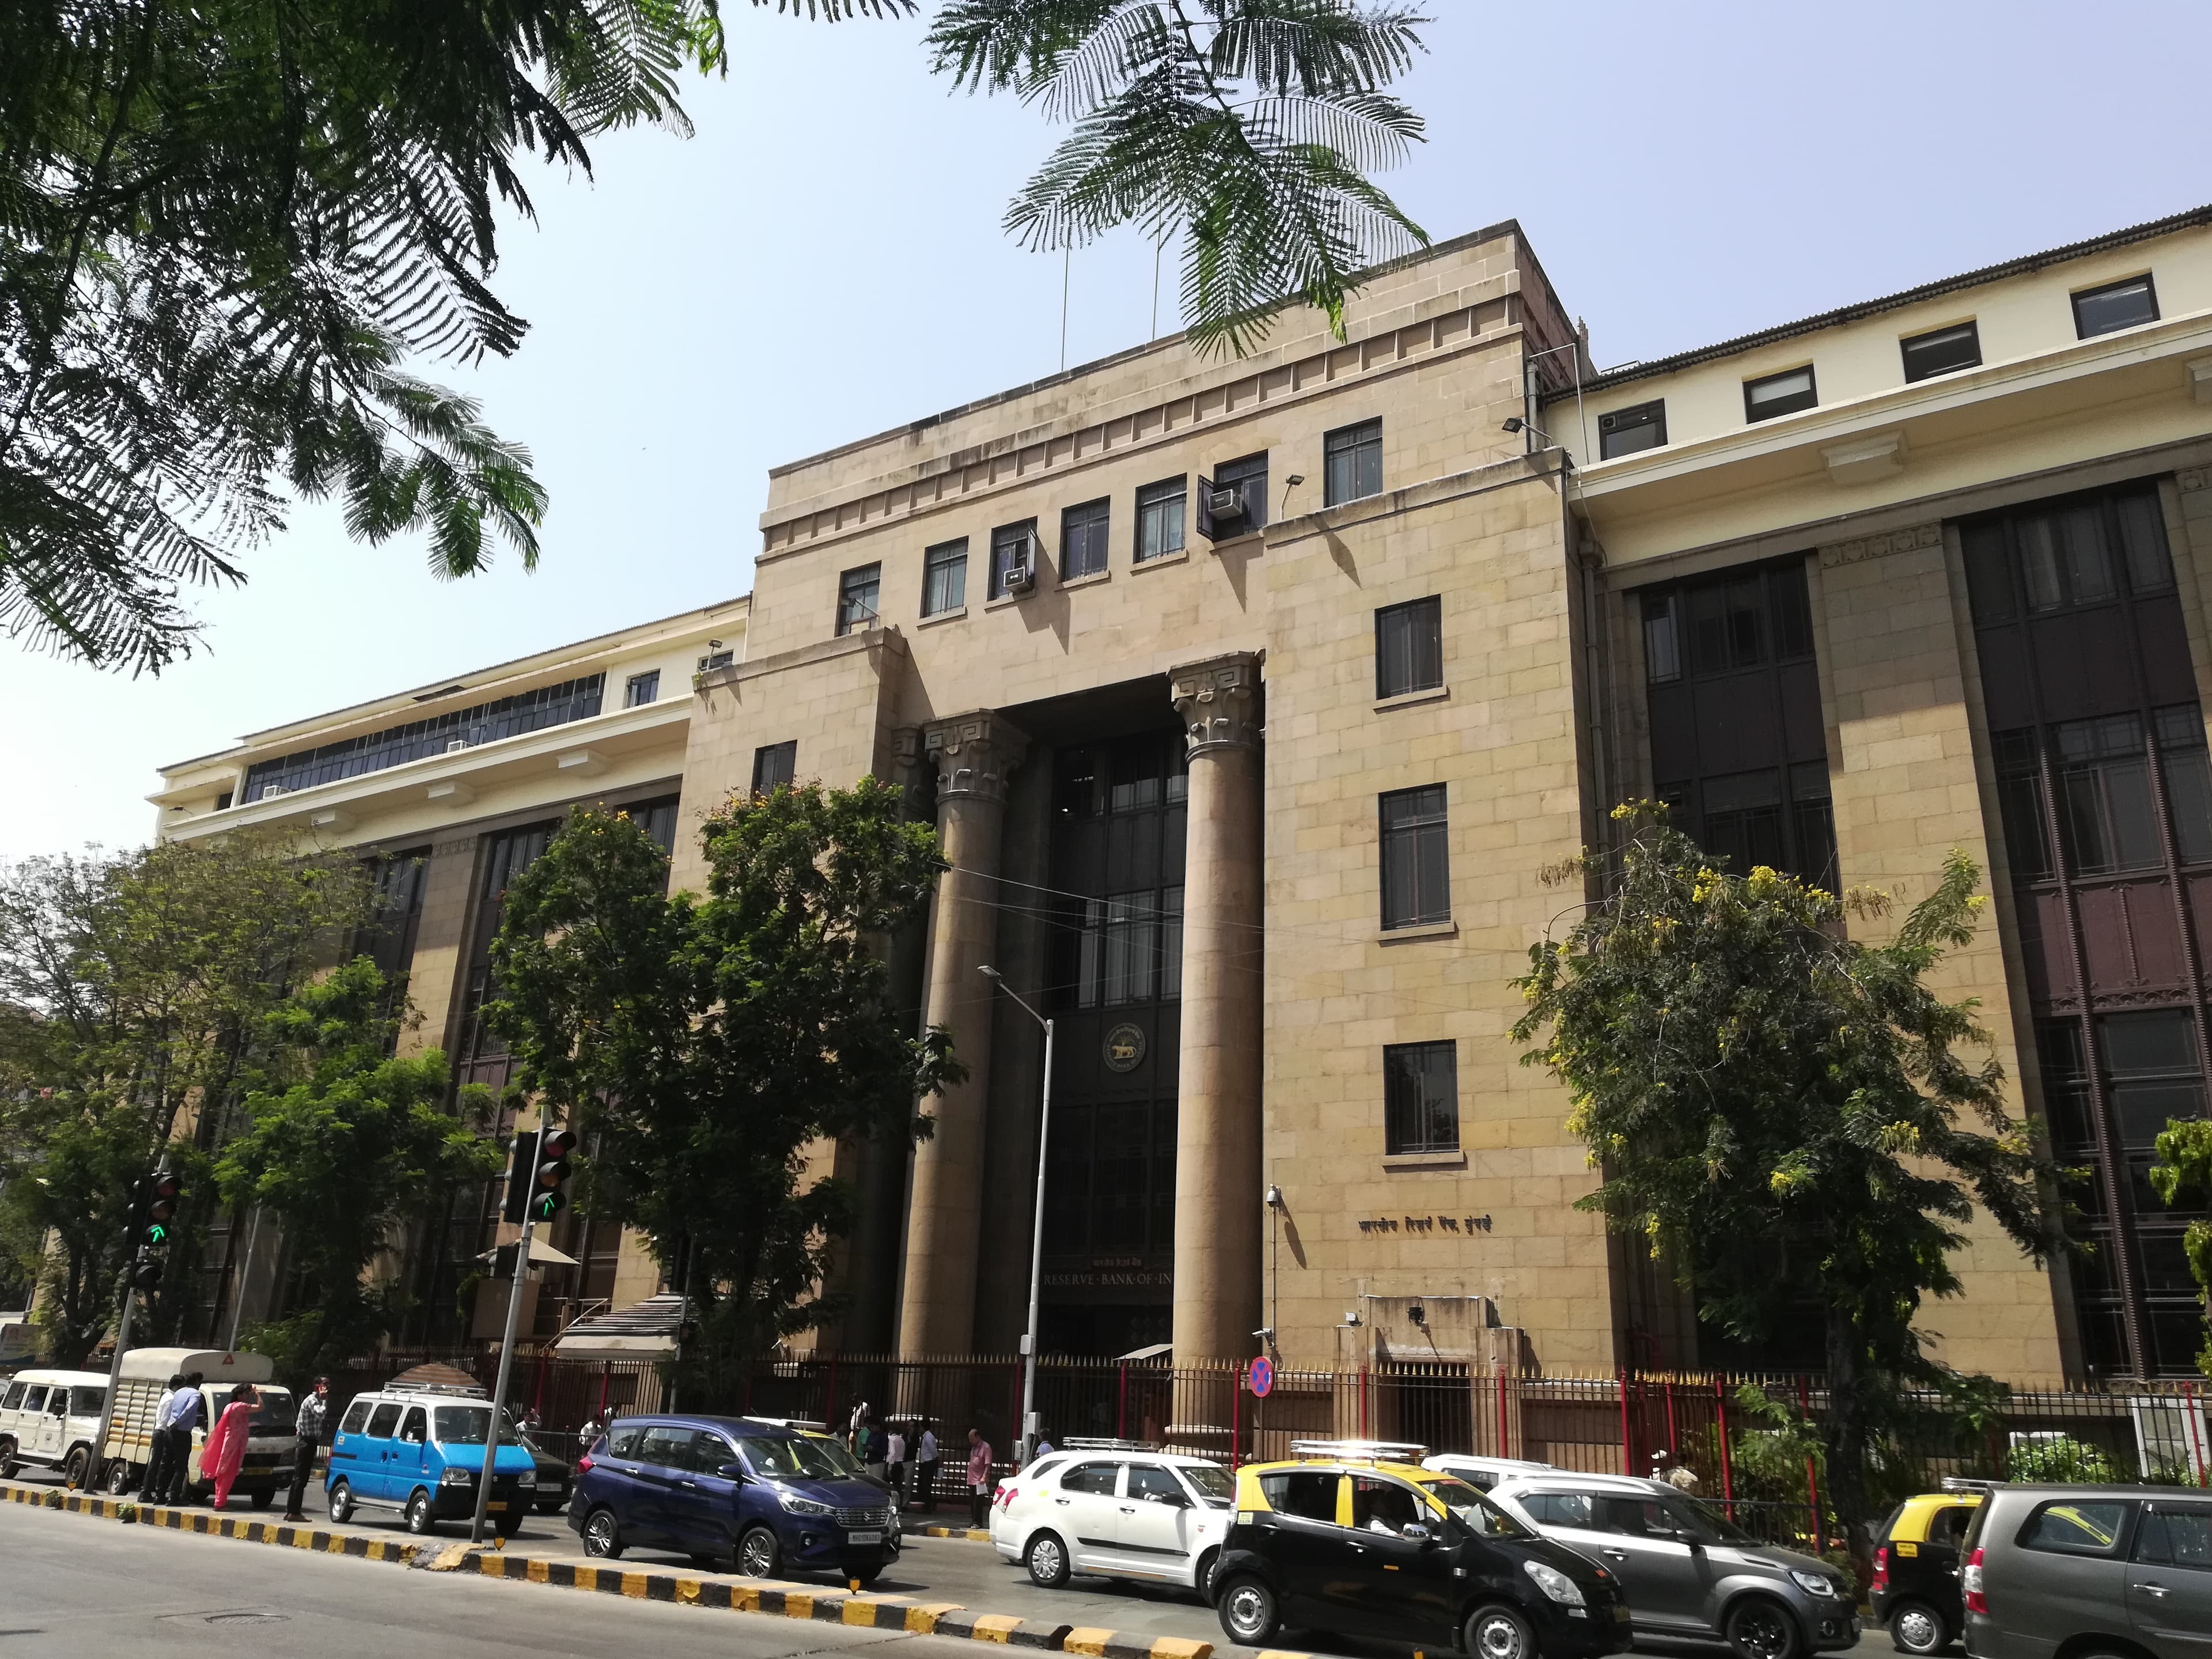
A comprehensive investigation into the Reserve Bank of India's adjusted liquidity management corridor and its immediate transmission into wholesale interbank repo rates.
| Operational Metric | Prev Benchmark | Recalibrated Level | Treasury Desk Impact |
|---|---|---|---|
| Standing Deposit Facility (SDF) | 6.25% | 6.25% (Floor) | Corridor floor maintained without unsterilized expansion |
| Marginal Standing Facility (MSF) | 6.75% | 6.75% (Ceiling) | Emergency window utilization down 42% month-on-month |
| Weighted Average Call Rate (WACR) | 6.68% | 6.52% | Aligned with policy target; volatility compressed to 6 bps |
| Net System Liquidity Balance | -₹1.85T | -₹0.38T | Structural deficit narrowing toward durable neutrality |
Executive Overview
This dispatch investigates recent structural developments in central banking, with particular focus on institutional execution, balance sheet implications, and regulatory scrutiny across domestic markets.
As institutional participation expands and capital costs remain recalibrated, market participants are confronting new operational trade-offs that challenge conventional underwriting and allocation frameworks.
Key Empirical Findings
• Standing Deposit Facility: Absorption corridor width narrowed to mitigate excessive intraday rate volatility.
• Net Interest Margin Pressures: Tier-1 lenders face 12-18 bps compression on variable rate asset books.
• Refinancing Dynamics: Primary dealers recalibrate 91-day Treasury Bill portfolios to match adjusted policy stance.
Market Structure & Structural Analysis
Our investigative desk analyzed transaction registries, regulatory disclosures, and institutional order books. The empirical evidence demonstrates a clear bifurcation between legacy operational models and technology-enabled execution corridors.
Key parameters examined include:
• Capital Velocity: The rate at which committed capital transforms into productive loan books or marketable securities.
• Counterparty Concentration: Aggregate exposure across primary clearing entities and bilateral non-bank lenders.
• Regulatory Compliance Overheads: Incremental costs associated with audit trails, data residency, and real-time capital adequacy monitoring.
“Market discipline cannot be outsourced to optimistic projections. When systemic liquidity tightens, only collateral quality and verifiable cash flows remain solvent.”
Forward Outlook & Strategic Implications
Over the coming quarters, market participants who maintain robust underwriting discipline and transparent liquidity buffers will command premium valuations and superior funding costs. Conversely, structures reliant on artificial yield enhancements face accelerated compression as oversight tightens.
FINBYTES EDITORIAL DISCLOSURE & COMPLIANCE
Reporting for this investigation was conducted independently by the Finbytes Capital Markets Desk in Mumbai. Sources at regulated entities were consulted under Chatham House Rule protections. Finbytes maintains strict newsroom isolation from commercial sponsorship and investment advisory divisions.