An analytical deep dive into the business models of India's dominant consumer payments applications operating on zero-merchant-discount-rate rails.
The Billion-Transaction Trap
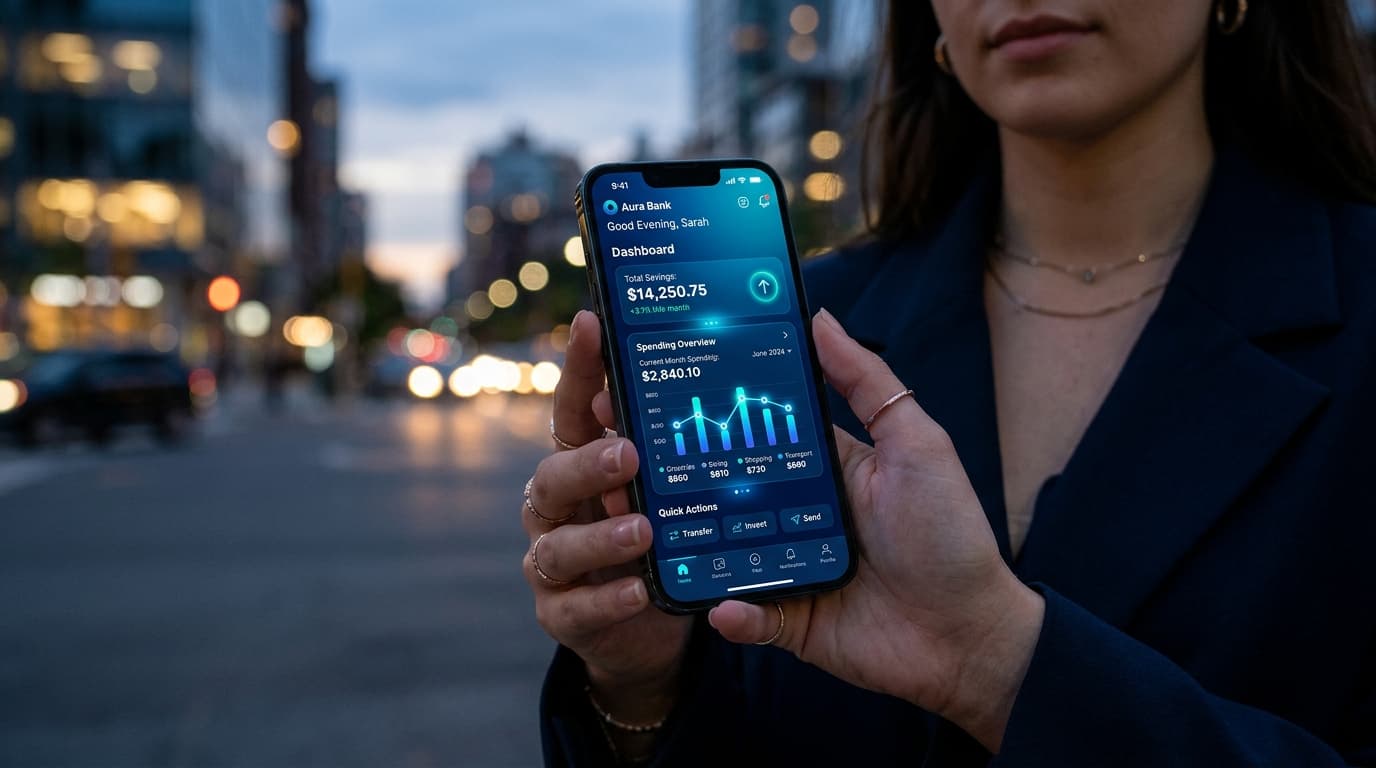
With 85% transaction share but zero interchange fees, payment giants construct merchant lending moats to survive. India's Unified Payments Interface is the undisputed champion of global retail payment infrastructure, processing billions of transactions monthly at sub-second speeds.
Yet for the private corporations that invested billions building consumer distribution, the core transaction layer yields zero direct interchange.
The Soundbox Cash Flow Engine
To monetize their network footprint, payment aggregators shifted focus from peer-to-peer transfers to merchant point-of-sale hardware.
Key mechanics include:
• Recurring Audio Subscriptions: Kirana stores pay ₹99 to ₹149 per month for audio payment confirmation boxes.
• Merchant Cash Advance: Transaction telemetry provides unparallelled real-time visibility into merchant daily turnover, enabling algorithmic micro-loans.
• Insurance Cross-Selling: High-margin micro-insurance products bundled directly into merchant settlement accounts.
Market Share Caps & Infrastructure Durability
The lingering question remains whether the regulatory 30% volume market cap will be strictly enforced or gradually deferred. For now, market participants must extract margin from tangential financial services while supporting heavy network infrastructure overheads.
“UPI is public digital infrastructure. Treating it as a proprietary revenue engine was always a flawed assumption; the real prize is underwriting the merchant behind the QR.”
FINBYTES EDITORIAL DISCLOSURE & COMPLIANCE
Reporting for this investigation was conducted independently by the Finbytes Capital Markets Desk in Mumbai. Sources at regulated entities were consulted under Chatham House Rule protections. Finbytes maintains strict newsroom isolation from commercial sponsorship and investment advisory divisions.